

Key Takeaways
- Rates and macro remain the key risks
- Stocks continue higher despite exceptionally weak breadth
- Bitcoin and Ethereum continue to tease big breakouts
Digital Asset Commentary
Geopolitical tensions, oil, global yields, and U.S. interest rates remain top of mind for markets. However, the recent softer-than-expected PCE data and weaker-than-expected jobs report have pushed the market’s pre-midterm rate expectations toward an 80% probability of a hold. Recent Fed commentary has also suggested growing reluctance to pursue another rate hike in the near term, providing some relief to risk assets.
The S&P 500 remains near record highs, but breadth beneath the surface is increasingly concerning. Only about 25% of S&P 500 stocks have positive 1-month returns, 36% are positive over 3 months, and just 45% are above their 200-day moving average. The cap-weighted S&P 500 is also dramatically outperforming its equal-weight counterpart. The RSP/SPY 3-year relative performance is around the 2nd percentile historically, highlighting just how narrow leadership has become.
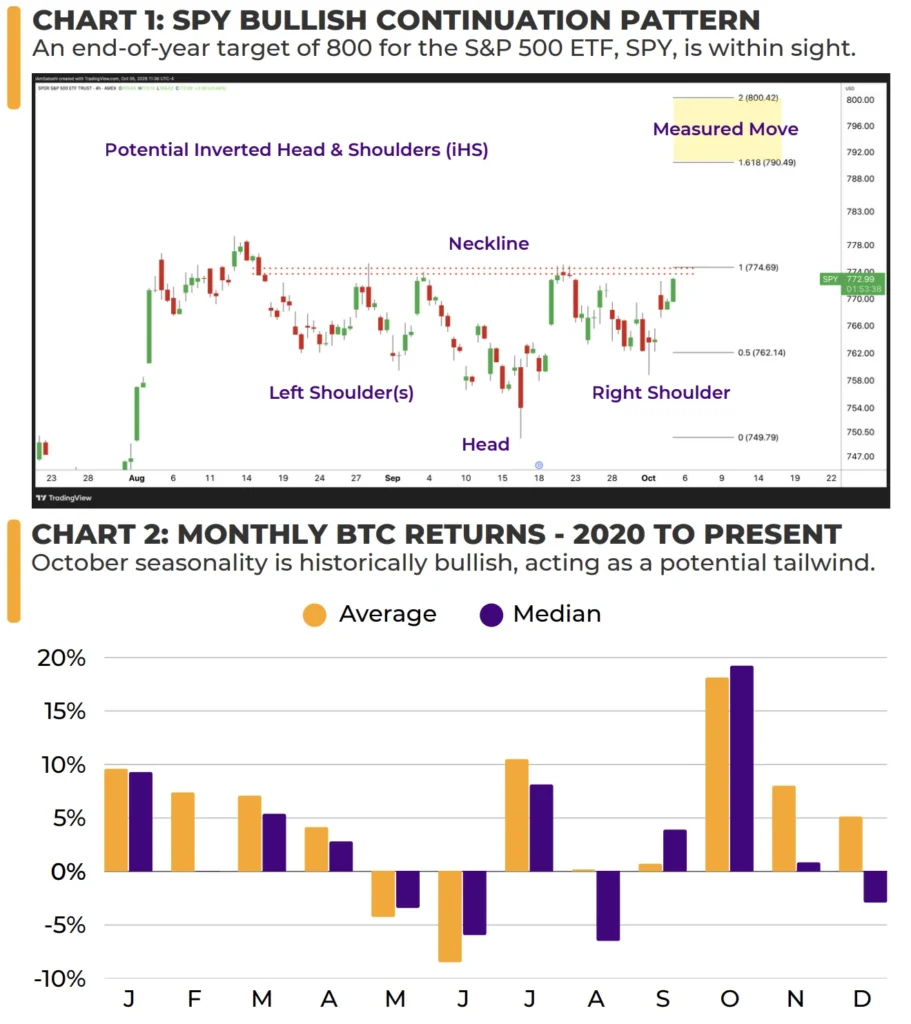
Despite the weak breadth, SPY continues to set up for 800 levels by year-end, supported by a bullish continuation pattern the inverted head-and-shoulders. A key characteristic of this pattern is a lower low flanked by at least two higher lows, followed by a breakout above the neckline. The measured move from the depth of the pattern points toward approximately 800. Meanwhile, QQQ and broader technology continue to push higher, with several technology indices already reaching new all-time highs.
Bitcoin was smacked down at $87k, while Ethereum was rejected above $2k. Both remain vulnerable to a rapid rise in rates and/or the dollar, but neither has broken down, instead, both continue to grind higher and tease a larger breakout. The measured move year-end target for BTC remains $100,000, while ETH could finish the year closer to $4,000 than $3,000.